Ualett
Cabicash Solutions, IncFinanceVerified
- 1.28K Reviews
- 4.6
- Downloads
- 500,000+
- Price
- Free
Screenshots
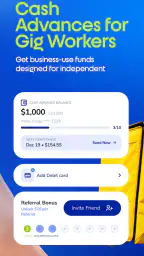
 Analysis by Appwesome
I approached Ualett as a practical finance app for people whose income does not always arrive on a predictable schedule. Its focus is clear from the way it is positioned: it is built for gig workers, rather than for someone looking for a broad banking replacement or a general budgeting dashboard. In my experience, that narrower purpose is both its most useful quality and the first thing to consider before installing it.
Ualett is free, developed by Cabicash Solutions, Inc, and available for users rated Everyone. It has reached over 500 thousand installs, with an average score of 4.6 from around 7.6 thousand ratings. Those figures suggest that the app has found a real audience among people who need financial tools that fit irregular work. Still, popularity alone is not a reason to hand over financial information. The better question is whether the app gives you enough clarity and control to make that exchange feel reasonable.
How Ualett fits into a gig worker’s financial routine
The typical gig worker does not necessarily have one payday, one employer, or a stable monthly pattern. Money can arrive after several separate shifts, deliveries, freelance tasks, or platform payouts. A conventional personal finance app may help categorize spending, but it may not feel designed around the timing problems that come with this kind of work. Ualett’s appeal is that it starts from that specific situation instead of treating irregular income as an exception.
I would consider it most relevant for someone who regularly needs to think about cash flow between jobs. A driver waiting for platform earnings, a courier managing fuel expenses, or a freelancer balancing several small payments may value a tool that speaks directly to the rhythm of independent work. The benefit is not simply having another finance app on the phone. The benefit is having an app whose intended audience understands that income can be fragmented and unpredictable.
That distinction matters when comparing Ualett with usual alternatives. A traditional bank app is generally strongest for established accounts, transfers, statements, and everyday payment management. A budgeting app is usually better when your main goal is tracking categories and building a long-term spending plan. Ualett makes more sense when the immediate problem is managing the financial pressure around gig work.
I would not automatically choose it for someone with a regular salary, a straightforward bank account, and no need to organize income from independent work. In that situation, a familiar banking app or a detailed budgeting service may provide a clearer overall picture. Ualett is more convincing when its gig-worker orientation matches your actual routine rather than merely sounding useful in theory.
What I look for before trusting a finance app
Finance apps deserve a different standard from entertainment or social apps. A small inconvenience in a game is forgettable; confusion around a financial account can affect decisions at exactly the wrong time. Before using Ualett seriously, I would read each permission request, review every screen involving accounts or income, and avoid tapping through setup simply to reach the main interface faster.
Other Stories to Read




The developer is identified as Cabicash Solutions, Inc, and the app has been available since August 21, 2018. That history gives the product a longer presence than a newly launched tool, but it does not remove the need for personal caution. I still want to know what I am agreeing to at each step, what information is being requested, and how easily I can change my mind later.
One practical habit is to install the app only from the official Android or iOS store, then check that the developer name matches Cabicash Solutions, Inc before beginning setup. I would also update the app through the store rather than relying on an old installation. The current version is 2.73.0, and it requires Android 8.0 or newer. Keeping the software current is especially sensible for a finance tool, although an update number by itself is not proof of security or quality.
The large number of users and the strong average rating can make Ualett feel familiar, but I would treat those signals as a starting point, not a guarantee. Reviews are most useful when they describe the exact workflow you plan to use. I would look for recent comments about account access, verification, notifications, support responses, and the clarity of financial actions rather than focusing only on short praise.
Account controls deserve attention during setup
The most important part of using a finance app is often not the home screen. It is the series of choices made during registration and connection. I would slow down whenever Ualett asks me to confirm identity, connect financial information, or authorize an action. If a screen uses broad language, I would read the accompanying explanation instead of assuming that every request is essential.
A useful approach is to separate “I need this to try the app” from “I am ready to use this for important financial decisions.” I can explore the service cautiously first, note which controls are available, and only then decide whether it fits my routine. This prevents the common mistake of committing sensitive information before understanding the product’s boundaries.
I would also keep account recovery in mind from the beginning. Before depending on Ualett during a busy workday, I would make sure I know how to regain access if I change phones, lose a password, or stop receiving a notification. A finance app is much easier to trust when its account controls are understandable before an emergency occurs.
Another sensible step is to review notifications after setup. Gig workers often receive many alerts from work platforms, payment services, and messaging apps. If Ualett sends important account notices, I would keep those enabled while reducing anything that feels unnecessary. This creates a better balance: important activity remains visible without allowing the app to become background noise.
Where data sensitivity becomes especially important
The sensitive moments are easy to identify. They include connecting accounts, reviewing income-related information, confirming a financial action, and checking a balance while rushed or distracted. I would avoid doing these tasks on a public network or while standing between jobs. The risk is not just someone seeing the screen; hurried taps can also lead to approving something I have not properly read.
Independent workers are often under time pressure. A driver may be checking finances before accepting another trip, or a freelancer may be trying to cover an expense before a payment arrives. In those situations, an app’s simplicity can help, but it can also encourage fast decisions. My rule would be to pause at any point where the app asks for confirmation, especially if the action affects access, transfers, or linked information.
I would not assume that a finance app should be given unrestricted access to everything on my phone. I would inspect the operating system’s permission screen and grant only what is clearly connected to the function I intend to use. If a permission does not make sense for my use case, I would deny it initially and see whether the app still works. That is a practical way to preserve choice without making unsupported assumptions about what Ualett does behind the scenes.
It is also worth checking the app after an operating system update. Phone settings can change, permissions may be reset or reintroduced, and notification behavior can look different. A quick review of Ualett’s permissions and account settings after a major update helps prevent old assumptions from becoming permanent access.
A realistic example from an irregular workday
Imagine I spend a morning completing several delivery jobs, then need to decide whether I can afford fuel and a repair before the next payout reaches me. I would use Ualett as part of that decision-making routine, but I would not treat its presence on my phone as permission to spend more than I can repay or replace. I would compare what I see in the app with the original platform records and my own bank activity.
That second check is important. No finance app should become the only source I consult when the decision involves a bill, a work expense, or a time-sensitive payment. I would use Ualett to organize my thinking, then verify the relevant amount and timing through the underlying account or work platform. This two-step habit is slower than relying on one screen, but it reduces the chance of acting on an outdated or misunderstood figure.
For a freelancer handling several small clients, I would use a similar workflow. I would separate money that has already arrived from money that is merely expected, keep a note of upcoming expenses, and avoid treating projected income as available cash. The app can support the routine, but the discipline still belongs to the user. That is one of the most important trade-offs: convenience helps with visibility, while careful verification protects against overconfidence.
What user agency looks like in daily use
For me, control means more than having an account menu. It means being able to understand what is happening, review choices before confirming them, and decide when to stop using a feature. I would look for clear explanations around connected information, recognizable confirmation steps, and settings that let me adjust notifications or access where appropriate.
I would also keep my own records. A simple monthly note with work income, expenses, and important account activity gives me an independent reference point. That is useful if I need to compare what Ualett shows with information from a bank or gig platform. It also makes switching away less stressful because my financial picture does not live entirely inside one app.
If I decided Ualett was no longer useful, I would first review the account and connected-service settings, save any information I need, and then follow the available account-management process rather than merely deleting the icon. Deleting an app is not always the same as closing an account or withdrawing permissions. That distinction is worth remembering with any finance service.
I would be especially cautious about using the app on a shared phone. A device can expose notifications, saved credentials, or open sessions even when the app itself is reputable. Screen locking, avoiding saved passwords on a shared device, and signing out when necessary are simple protections that preserve more control.
Who should use it and who should look elsewhere
Ualett is a reasonable candidate for gig workers who want a finance tool shaped around irregular earnings and who are willing to review account choices carefully. It may also suit someone who finds broad budgeting apps overwhelming and prefers a more focused experience. The strongest match is a person whose financial questions begin with “When will my work money be available?” rather than “How do I analyze every category in my household budget?”
I would be less likely to recommend it as the only financial app for someone managing investments, complex household finances, multiple businesses, or detailed tax records. A dedicated budgeting or accounting product is usually better for those jobs. Likewise, someone who wants a full-service bank relationship may prefer an established banking app that already handles their deposits, payments, statements, and support in one place.
There is also a behavioral limitation. If you tend to accept financial prompts quickly without reading them, no interface can fully protect you from poor decisions. Ualett may make gig-related money management more approachable, but it cannot replace checking original records, planning for taxes, or maintaining an emergency buffer. I see it as a focused aid, not a substitute for financial judgment.
My cautious verdict after weighing convenience and control
Ualett stands out because it is aimed at a real problem: the uneven timing and pressure of gig-work income. Its free price lowers the barrier to trying it, and its established presence, current version, and strong user response make it worth investigating for the right audience. I appreciate that its usefulness depends on a specific situation rather than pretending to be the perfect answer for every financial task.
My recommendation comes with a clear condition: use it deliberately. Read setup screens, inspect permissions, keep notifications under control, verify important figures against their original source, and maintain your own basic records. Those habits are not signs that the app is untrustworthy; they are sensible safeguards whenever a mobile service touches financial information.
For a gig worker who wants a focused companion for irregular income, I think Ualett is worth trying. For someone seeking a complete bank replacement, advanced budgeting suite, or accounting system, I would choose a more specialized alternative. The best reason to install it is not its rating or install count, but whether its focused purpose matches the way you actually earn and manage money.
In the end, I would keep the app only if its controls feel understandable and its workflow genuinely reduces friction during my workweek. If it helps me make better-informed decisions without encouraging rushed approvals or dependence on a single source, it has a useful place on my phone. If the setup, permissions, or account choices feel unclear, I would step back and use a simpler tool until I could evaluate those decisions properly.
Highlights
- Fast access to earned wages through the app
- Simple interface makes balance tracking easy
- Useful notifications help monitor payment activity
- Can reduce reliance on high-cost short-term loans
- Convenient mobile access without visiting a branch
Limitations
- Availability may depend on employer or payroll integration
- Fees can apply depending on the advance or transfer
- Advance limits may be lower for new or occasional users
- Bank transfer timing can vary
- especially on weekends
- Requires personal and employment information during setup
Frequently Asked Questions
01What is Ualett and what can I use it for?
Ualett is a financial app designed to help users manage everyday money tasks from a mobile device. Depending on your location and eligibility, it may provide access to services such as digital payments, money transfers, account management, or other financial tools. Available features can vary by country, so review the official terms and product details before relying on it for important transactions.
02How do I create an account on Ualett?
To register, download Ualett from an official app store and follow the on-screen sign-up process. You will generally need to provide personal information, a valid phone number or email address, and possibly identification documents for verification. Make sure your details are accurate and that you meet the eligibility requirements. Account approval may not be immediate if additional checks are required.
03Is Ualett safe to use for managing money?
Ualett may include standard security measures such as password protection, account verification, encrypted connections, and transaction monitoring. However, no financial app is completely risk-free. Use the latest official version, enable available security options, avoid sharing verification codes, and contact support immediately if you notice suspicious activity. Always read Ualett’s privacy policy and user agreement.
04Are there fees or limits when using Ualett?
Ualett’s fees, transfer limits, withdrawal rules, and supported payment methods may depend on your country, account type, verification status, and the specific service you use. Some operations may be free while others can include service or transaction charges. Before confirming a payment or transfer, carefully check the displayed cost, applicable limits, and any exchange-rate information.
05What should I do if I cannot access my Ualett account or a transaction fails?
If you cannot log in, first check your internet connection, update the app, and use the official password or account-recovery option. For failed or delayed transactions, avoid repeating the payment until you confirm whether the first attempt was completed. Save receipts and reference numbers, then contact Ualett support through the in-app or official support channel. Never give your password or verification code to anyone.


